


Industry Insights
Words of wisdom from our business insurance experts.
Data Center Construction Insurance: Builder's Risk, DSU, and Project Cargo
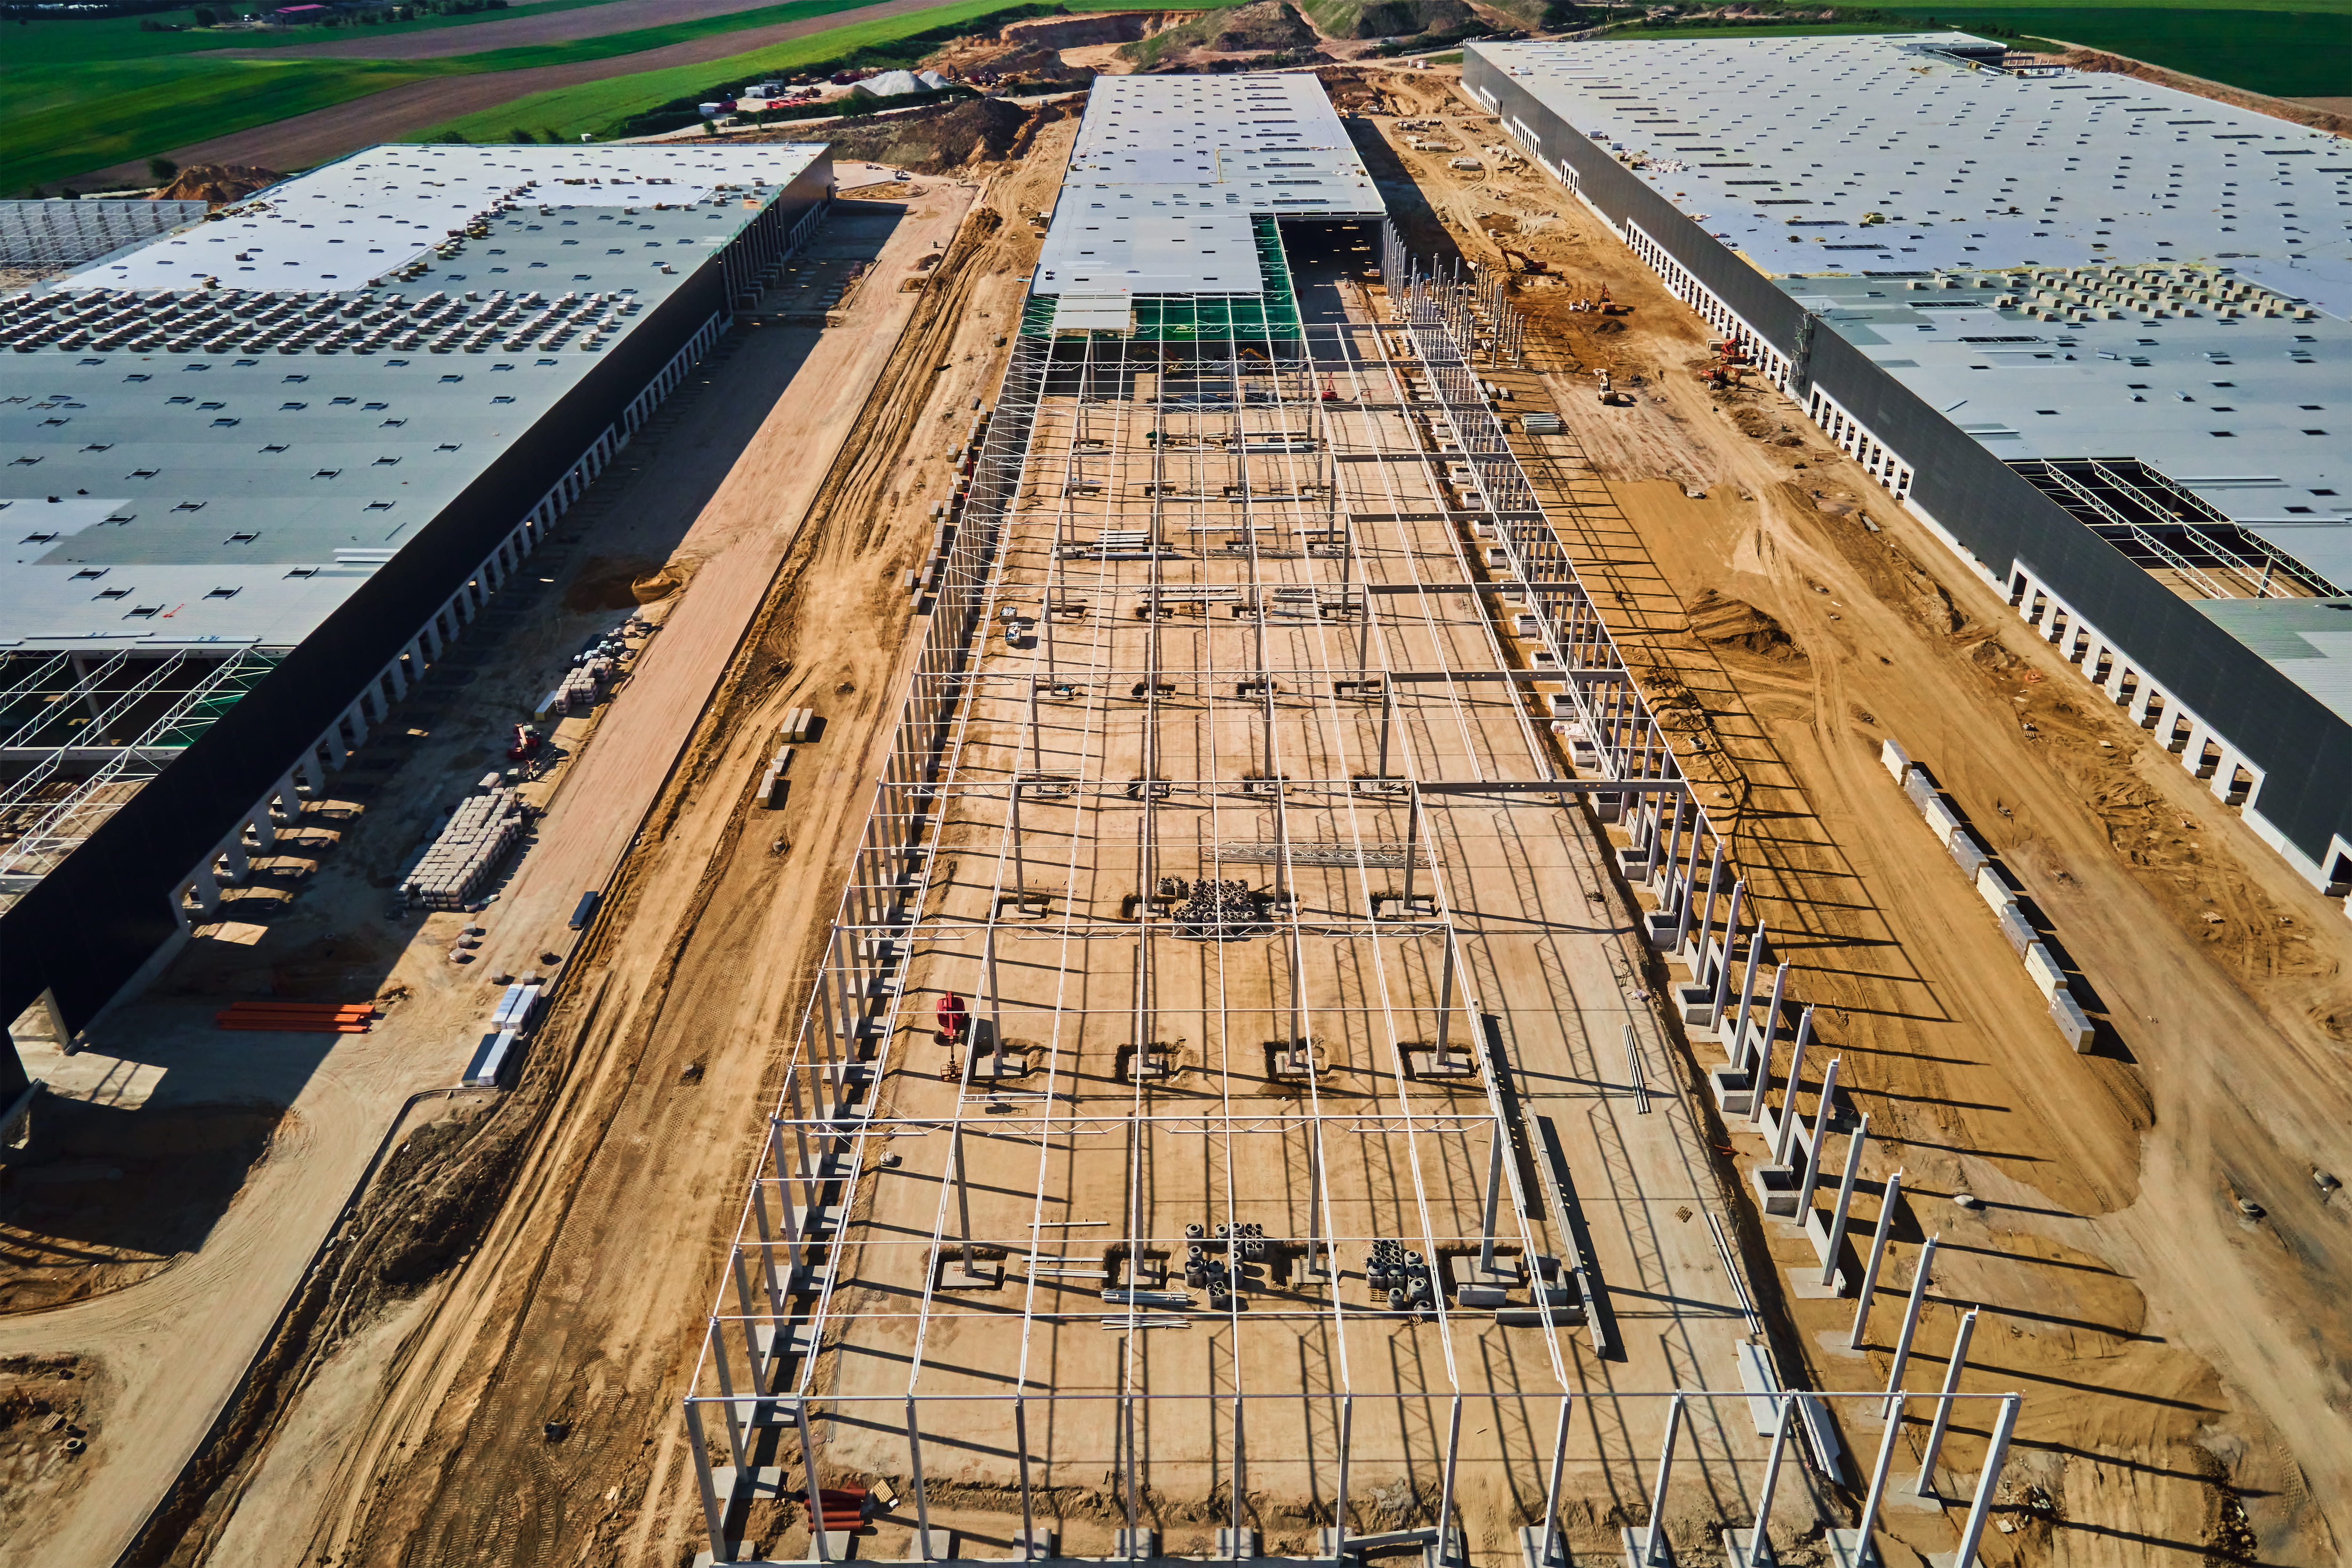
Our companion guide to data center insurance covers the property, business interruption, cyber, and related lines a facility carries once it becomes operational. This piece is about the phase before any of that exists: the eighteen to thirty-six months when a data center is a construction site, a supply chain, and a financing package rather than a running business.
That build phase carries some of the largest — and most misunderstood — exposures in the whole project. A data center under construction concentrates hundreds of millions of dollars of value on one address, much of it in equipment that hasn't arrived yet and can't be reordered quickly. Data center construction insurance is the set of coverages that sits over that window: builder's risk for the works themselves, project cargo for the long-lead gear in transit, and delay in start-up (DSU) for the revenue a finished-but-late building can't yet earn. Getting the structure right matters because, as Engineering News-Record has reported, billions of dollars of data center construction risk may remain uninsured or retained by developers — not only because programs are arranged late, but because project values, probable maximum loss (PML) assumptions, catastrophe aggregation, and DSU requirements can exceed conventional market capacity. ENR notes that some hyperscale sites carry insurable values in the tens of billions, of which conventional structures may cover only a fraction.
Quick answer: Data center construction insurance is the coverage that protects a facility during the build phase, before it becomes an operating business. The three pillars are builder's risk (physical loss or damage to the structure and installed equipment during construction), project cargo / marine transit (high-value, long-lead equipment like transformers and switchgear while it's being shipped and stored), and delay in start-up or DSU (the revenue and financing costs lost when a covered event pushes back the completion date). Wrap-up liability, contractors' pollution, and professional/design liability typically round out the program. Developers, general contractors, and lenders usually share an interest in these policies, so terms are best negotiated before construction financing closes rather than after.
What does data center construction insurance actually cover?
There's no single "data center construction" policy. It's a coordinated set of covers, each responding to a different slice of the build. Understanding the pieces is what lets a developer or contractor see where the gaps tend to open up.
The point of laying these out side by side is that the exposures don't line up neatly with a single policy. A loss can trigger builder's risk and DSU together, or sit in the gap between cargo and builder's risk if the two aren't written to dovetail. That coordination — not just the individual limits — is usually where a build gets under- or over-insured.
Why is delay in start-up (DSU) the hardest part to get right?
Of all the build-phase covers, delay in start-up tends to be the one that's underestimated. Builder's risk pays to repair the damage; DSU pays for the time the damage costs you. On a facility with contracted capacity waiting to come online, that time can be worth more than the physical repair itself.
One distinction is especially important, and often misunderstood: DSU is not a general schedule-delay policy. It typically requires a covered physical loss under the underlying property or builder's-risk form. Procurement delays, utility interconnection or permitting problems, design disputes, defective workmanship, supplier default, and ordinary contractual slippage may not trigger DSU at all unless the program includes specific extensions or a separate risk-transfer solution applies. On a data center, where the schedule can slip for reasons that have nothing to do with physical damage, that distinction is where expectations and coverage most often diverge.
A few other things make DSU difficult to place at adequate limits. It's priced off the revenue the finished facility is expected to earn, so the values have to be modeled before the building exists. Because DSU is priced around projected income, financing obligations, the period of indemnity, and the complexity of returning the facility to service after a loss, it can become a major component of total construction-insurance cost. The period of indemnity — the maximum period for which DSU can respond after a covered loss — also has to be long enough to reflect not just repair, but replacement, re-procurement, testing, commissioning, and return-to-service time.
That last point is where data centers differ from ordinary construction. If a transformer is destroyed and the replacement carries a lead time measured in many months, a period of indemnity that assumed a quick rebuild may run out before the facility can actually open. Matching it to genuine equipment lead times and the full path back to commercial service — rather than to the construction schedule alone — is one of the details most worth pressure-testing before binding.
A note on how these covers interact: builder's risk, DSU, and project cargo are generally intended to work together, but they're often written on separate forms with their own sub-limits, deductibles, and waiting periods. Whether a single event flows cleanly across all three depends on the specific policy language, so the interaction is worth confirming rather than assuming.
What about the equipment that hasn't arrived yet?
One of the features that makes data center construction unusual is how much of the project's value is sitting in a factory or on a ship rather than on the site. Transformers, switchgear, backup generators, and cooling systems are high-value, purpose-built, and frequently sourced internationally, with lead times that can stretch across the better part of the construction schedule.
That creates two related exposures. The first is transit and storage: a transformer damaged in shipping, or while it waits in a staging yard, is a loss that builder's risk may not fully address if the cover is written around the site rather than the supply chain. Project cargo (sometimes called marine cargo or project marine) is designed to sit over that journey. The second is the schedule knock-on: because a damaged long-lead item can't simply be reordered off the shelf, a transit loss can quietly become a delay loss — which is why cargo and DSU are best reviewed together rather than in isolation.
For developers, the practical implication is that the equipment procurement timeline and the insurance program are really the same conversation. A long-lead order placed before the cargo and DSU terms are settled can leave a window where the most valuable, least replaceable components are moving without the coverage that reflects what a loss would actually cost.
When does construction cover end and operational cover begin?
Data centers have an unusually consequential handover. A facility can be physically complete but not ready for commercial service: systems have to be tested under load, equipment has to be energized, and on a large campus some buildings may transition to operations while adjacent phases are still under construction. That in-between period — testing, commissioning, energization, phased handover — is where builder's risk and the operational property / business-interruption program have to meet cleanly, and it's a common source of gaps.
Two questions tend to matter most. First, does the builder's risk program actually address testing, commissioning, and energization, or does cover contemplate a "completed" building that a live-load test then falls outside of? Second, is there a defined trigger for when construction cover ends and operational cover begins — ideally with a documented overlap rather than a hard cutoff at "completion," which can be ambiguous on a phased build. Purpose-built data center facilities have started to address this directly, with embedded commissioning cover and DSU values that step down automatically as phases go live; the fact that the specialist market treats the transition as its own problem is a good signal that a build should too.
There's a related, non-damage exposure worth naming here: grid interconnection and utility timing. A facility can be finished and still unable to earn revenue because the power connection isn't ready. Because DSU generally responds only to a covered physical loss, a missed interconnection date, a utility delay, or a permitting problem may fall outside the program entirely unless a specific coverage extension is available and negotiated, or the commercial exposure is addressed through another contractual or project-risk mechanism. On a data center, where power availability is often the true gating item, that's a gap worth identifying early rather than discovering at commissioning.
How much does data center construction insurance cost?
Construction insurance cost is driven by the specifics of the project — completed value, location and natural-catastrophe exposure, construction type, the contractor's experience with data center builds, and above all the DSU limit and indemnity period — so any figure quoted in the abstract can be misleading. What can be said is directional rather than precise.
Broadly, the largest cost drivers on a data center build are the completed-value builder's risk limit and the DSU component layered on top of it. Because DSU is priced around projected income, financing obligations, the period of indemnity, and the complexity of returning the facility to service after a loss, projects with long indemnity periods or high contracted-revenue values will often see insurance costs weighted heavily toward that single line. Natural-catastrophe exposure at the site (wind, flood, wildfire, hail) can move the builder's risk rate significantly, and a site in a higher-hazard zone may face both higher pricing and tighter terms.
The more useful framing than a rate is capacity: whether the market will offer enough limit for a build of this size on acceptable terms. That's the constraint the market has been responding to. Marsh's "Nimbus" facility , launched in 2025 as a dedicated facility for large-scale data center construction, has offered limits reported in the billions inclusive of delay-in-start-up and business interruption cover, and Aon expanded its Data Center Lifecycle Insurance Program to up to $5 billion in July 2026 for construction all risks, DSU, and property damage / business interruption, alongside separate project-cargo capacity of up to $500 million. The growth of these purpose-built facilities reflects the challenge of assembling adequate limits and consistent terms for projects at this scale through conventional construction-market placements. Program capacity, attachments, and terms can change, so current availability should be confirmed directly with the market rather than taken from any single published number.
Who needs to be on the policy — and who decides?
Data center builds usually involve at least three parties with an insurable interest in the construction program, and the coverage works best when their interests are reconciled up front rather than argued over after a loss.
- Developers / owners carry the ultimate exposure to the completed value and, through DSU, to the revenue a late facility can't earn. They typically drive the builder's risk and DSU decisions.
- General contractors and EPC firms may be responsible for arranging builder's risk under the construction contract, while liability is often handled through an owner-controlled or contractor-controlled insurance program (OCIP or CCIP). They also carry their own liability, professional, and pollution exposures depending on the contract structure. A wrap-up is a liability structure rather than a form of builder's risk, so the two should be coordinated but treated as separate parts of the program.
- Lenders and investors financing the build often require defined policy interests — such as mortgagee, loss-payee, or lender's-loss-payable protections — along with agreed limits and DSU terms designed to support debt service if completion slips. Those requirements are frequently incorporated into the construction loan agreement.
On phased campuses and expansions, the program should also address damage to existing or operational property caused by ongoing construction activities — that exposure may not sit cleanly within a standard builder's risk form, which is written around the works under construction rather than the buildings already running beside them.
Because lender requirements, the construction contract, and the insurance program all reference each other, the sequence matters. Terms negotiated before construction financing closes tend to hold together; terms retrofitted afterward are where mismatches — a DSU indemnity period shorter than the loan assumes, or a sub-limit a lender won't accept — tend to surface. A specialist broker's role here is largely to make those documents agree with one another before ground breaks.
The build-to-operations handoff, stage by stage
It helps to see the whole program as a sequence rather than a single policy. Each stage of a data center project carries a different dominant exposure and a different question the insurance program has to answer.
None of these stages is insured by a single form, which is exactly why the coordination — not just the individual limits — is where a program holds together or comes apart.
Questions to work through before construction financing closes
A short checklist tends to be more useful than a coverage lecture. Before binding a construction program, it's worth being able to answer:
- Is the builder's risk limit based on the project's insured values at risk — including owner-furnished and long-lead equipment — rather than simply today's spend, and has the structure been tested against the lender's requirements, probable maximum loss (PML), and available market capacity?
- Does the DSU period of indemnity reflect real equipment lead times — including the time to re-source a destroyed transformer or switchgear unit, plus testing and return to service — and not just the construction schedule?
- Does the DSU analysis clearly distinguish covered physical damage from non-damage delays such as utility interconnection, permitting, supplier default, design changes, and schedule slippage — and is anything expected to bridge those non-damage delays?
- Is project cargo in place for the high-value equipment in transit and storage, and are owner-furnished equipment, off-site storage, and temporary locations scheduled consistently across builder's risk and cargo so there's no gap at delivery and installation?
- Does the policy expressly address testing, commissioning, energization, and phased handover with a documented handoff — including any overlap period — between builder's risk and the operational property / business-interruption program?
- For multi-building campuses, has the structure been tested against PML and catastrophe aggregation rather than only against total construction cost — and does it address damage to already-operational phases caused by ongoing construction?
- Do the **lender's requirements** — such as limits, mortgagee or lender's-loss-payable protections, loss-payee status, and DSU terms — match what the policy actually provides, in writing?
- Are liability, pollution, and professional/design exposures placed consistently, whether through a controlled program (OCIP/CCIP) or individual contractor policies?
- Has anyone confirmed how builder's risk, DSU, and cargo interact on a single loss, given they're often separate forms?
None of these have universal answers — they depend on the project, the contract, and the market at the time — but they're the questions that tend to separate a program that holds up under a claim from one that reveals a gap at the worst possible moment.
Frequently asked questions
What is data center construction insurance?
It's the coordinated set of coverages that protects a data center during the build phase, before it becomes an operating facility. The core pieces are builder's risk (physical damage to the works during construction), project cargo (high-value equipment in transit and storage), and delay in start-up or DSU (lost revenue and financing costs when a covered event delays completion), usually alongside construction liability, pollution, and professional/design cover.
How is it different from the insurance a data center carries once it's operating?
An operating facility carries property, business interruption, cyber, equipment breakdown, and related lines that respond to a running business. Construction insurance responds to the temporary, higher-concentration risk of the build itself — a site full of installed and in-transit equipment with no revenue yet — and generally winds down as the facility reaches completion and transitions to its operational program.
What is delay in start-up (DSU) coverage?
DSU — sometimes called advance loss of profits — can cover insured loss of gross profit or revenue and certain continuing or additional costs when a *covered physical loss* delays a project's completion. The exact measure of loss, waiting period, deductible, limits, and period of indemnity depend on the policy. Importantly, DSU is not a general schedule-delay policy, so ordinary procurement, utility interconnection, permitting, or contractual delays may fall outside it unless a specific coverage extension is available and negotiated. For projects with contracted capacity and substantial debt-service obligations, DSU can be one of the most financially significant parts of the construction program.
Why is long-lead equipment such a big part of the conversation?
Transformers, switchgear, and generators are frequently custom-built and sourced internationally, with lead times that can span much of the construction schedule. That concentrates value in transit and storage (a project cargo exposure) and means a damaged component can't be quickly replaced — turning a physical loss into a delay loss. Coordinating cargo and DSU around real lead times is one of the details most worth getting right.
Who typically arranges data center construction insurance?
Responsibility varies by contract, but developers, general contractors, and lenders all usually have an interest in the program. Because their requirements reference each other — and are often written into the construction loan — the coverage is best structured before financing closes. A specialist broker generally coordinates the pieces so the policy, the contract, and the lender's requirements agree.
*This article is general information, not insurance or financial advice. Coverage terms, limits, and exclusions vary by policy and by insurer; confirm the specifics of any program with a licensed advisor. Last reviewed: September 2026.*


management specialist